Research-powered trading
Introduction
We’re a team of engineers, mathematicians and scientists working on one of the world’s hardest quantitative challenges: global financial markets. We combine statistical modelling, machine learning and high-performance compute to build models and trading systems that generalize, adapt and survive live deployment.
Focus areas
We trade at scale, across a universe of quantitative problems. Our research teams work across the full model lifecycle: defining the problem, selecting data, testing hypotheses, building simulations, analyzing failures and turning models into systems that improve how we trade.
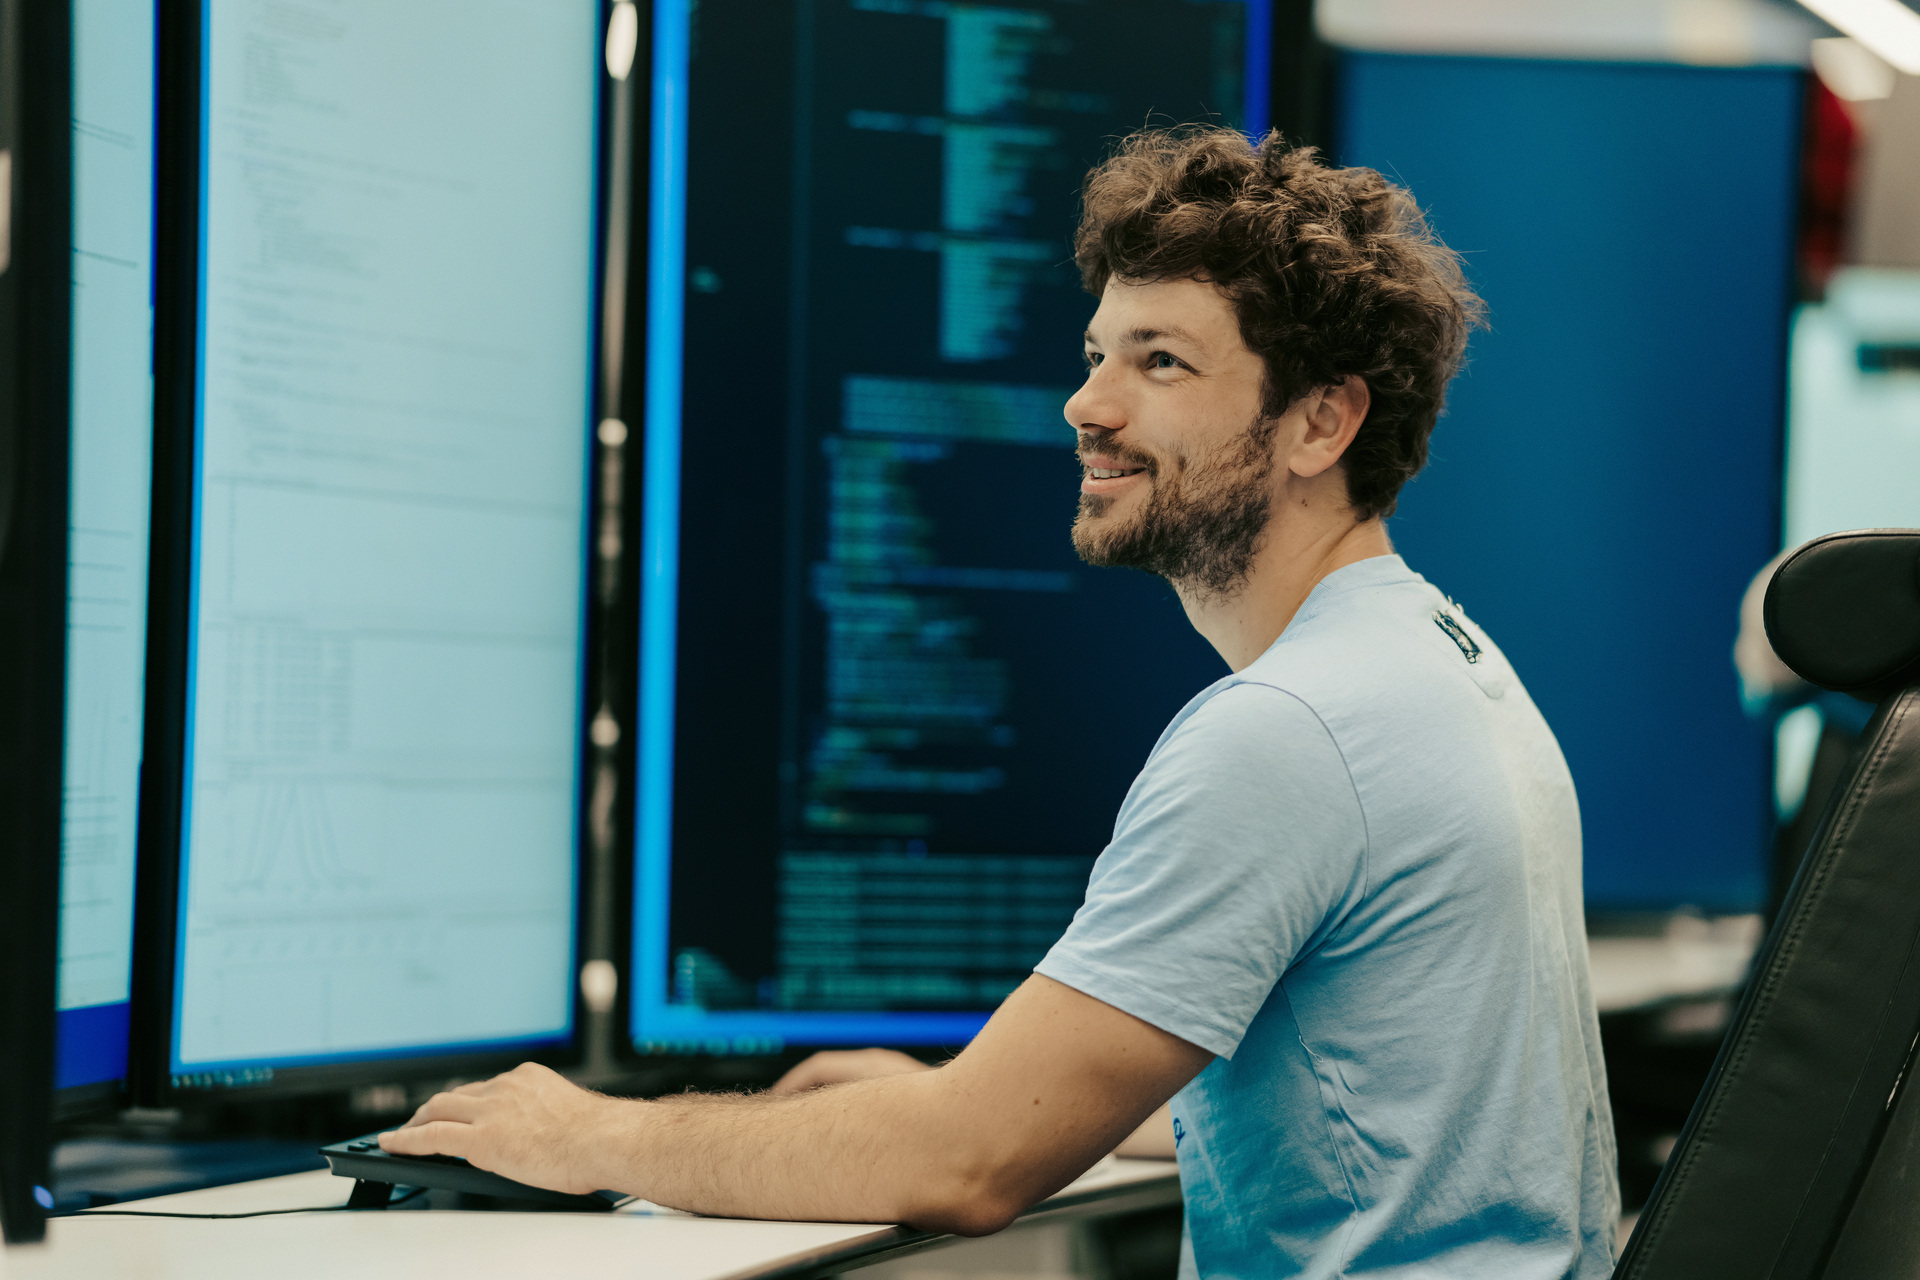
Machine learning for signal discovery

Pricing and forecasting models
Testimonials
“Markets are very non-stationary. Distributions shift over time, relationships change, and what worked before can stop working. That’s why the problem never stays solved.”
“It’s not a black box where you optimize a metric and stop. You might improve a model metric, but if it doesn’t improve the downstream strategy, you need to work with traders and engineers to understand why and redesign it.”
“Our compute infrastructure gives researchers the power to iterate at the speed of their ideas.”
An environment built for research velocity

Research at the frontier


Pushing research where standard models stop working
AI labExplore roles
Senior Performance Researcher
Shanghai
ExperiencedQuantitative Research & Machine LearningExperiencedQuantitative Research & Machine Learning- GraduateQuantitative Research & Machine LearningGraduateQuantitative Research & Machine Learning
- GraduateQuantitative Research & Machine LearningGraduateQuantitative Research & Machine Learning